Paying Over $50,000 for Solar? Read This Before You Sign
A $50,000-plus solar proposal is not necessarily a $50,000 solar-panel price. Separate the roof, electrical work, solar equipment, financing and real utility savings before signing. Includes an LADWP case study, official resources and questions that can save you money.
Quick answer: a $50,000-plus quote is not decision-ready until every cost reconciles
A $50,000-plus proposal is not automatically overpriced. Before signing, reconcile the solar-only cash price, roof and electrical scope, battery cost if any, amount financed, APR, total of payments, projected production and the utility bill that remains. Do not compare an all-in project total with a solar-only benchmark.
A proposal exceeding $50,000 can include solar panels, roof replacement, electrical service work, batteries and years of loan interest. These are different purchases with different useful lives. Some may be necessary for safety; others are optional or may be handled at a lower cost. The final number alone cannot tell you whether a quote is fair.
Before choosing Tesla or any local contractor, compare the scope, the cash price, projected electricity savings, the utility's actual billing rules and the total financed cost. A good professional should welcome the questions in this guide, explain the math and put the answers in writing.
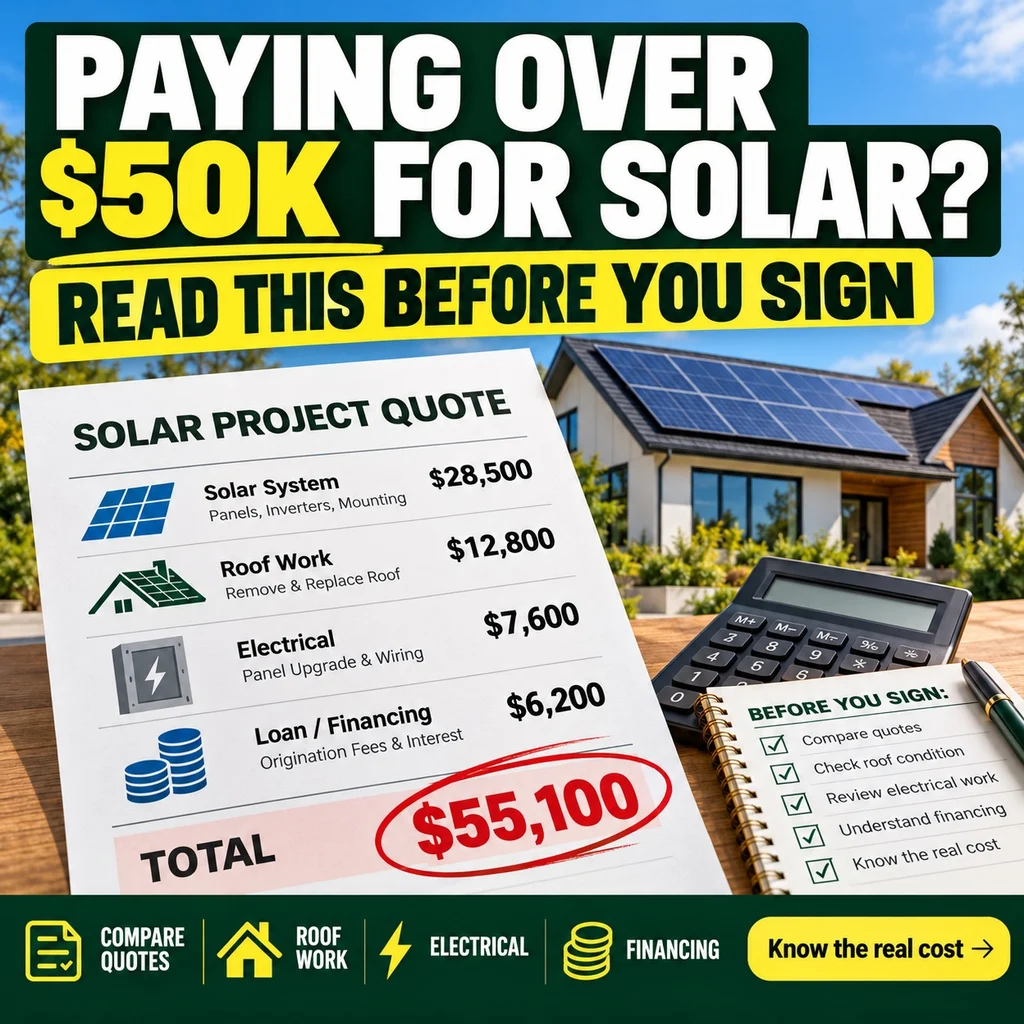
This article is general homeowner education with a Los Angeles Department of Water and Power (LADWP) case study. The cover image uses a separate illustrative sample quotation, not the actual LADWP/Tesla proposal; its example line items, including a financing line, should not be treated as an actual contractor invoice or as a substitute for itemized lender disclosures. It is not an endorsement or accusation about any company. Costs depend on the property, and local utility and incentive rules differ.
Real homeowner example: an approximately $60,265 all-in proposal
An LADWP homeowner described a 13.44 kW solar proposal with solar equipment and installation priced at $37,497, roof work at $17,470 and a main electrical panel upgrade at $4,130. The stated total after taxes and discounts was approximately $60,265. Financing was described as 15 years at 7.24% APR with a $530.64 monthly payment.
First reconciliation: $37,497 + $17,470 + $4,130 = $59,097. That is $1,168 below the stated approximately $60,265 total. Taxes, fees or quote revisions might explain the difference, but the homeowner should request an itemized reconciliation. Second reconciliation: if the entire $60,265 were financed for 180 equal monthly payments at a nominal 7.24% annual interest rate, the mathematical payment would be approximately $549.80, not $530.64. The stated $530.64 for 180 months totals $95,515.20; the modeled $549.80 totals approximately $98,963.49. APR and the loan's interest rate are not always identical, and actual disclosures could involve a lower principal, different timing, down payment or charges. Obtain the lender's written amount financed, interest rate, APR, payment schedule and total of payments rather than assuming either calculation is the contract.
Now separate the work: $37,497 divided by 13,440 DC watts is about $2.79 per watt for the solar portion, before investigating its scope or any discount. Do not divide the $60,265 total by the panel wattage and call the result the solar equipment price. Roof replacement and electrical work must be compared independently. Also, no battery is listed in this homeowner's quote; do not assume one is included.
A 13.44 kW nameplate rating describes DC generating capacity—not annual kWh production, not real-time output in all weather, and not proof of the right size. Request the projected annual kWh, monthly production, shading and roof assumptions, and match them with the home's last 12 months of actual electric usage.
1. Is a $50,000-plus project reasonable? Break it into three bids
Compare solar-only cash prices in dollars per DC watt, with identical equipment specifications, permitting and warranties. Price per watt is a useful screen but not a verdict: roof difficulty, structural engineering, multiple roof planes, inverter selection, service work and regional labor can change the cost. A low bid that excludes necessary work can be more expensive in the end.
For the roof, ask a licensed roofing contractor for a written assessment: Is a full replacement required, or would targeted repairs suffice? What square footage and roof material are included? Are decking, underlayment, flashing, permits, tear-off and disposal included? A $17,470 roof price means little without roof size, existing material and scope.
For the electrical work, request an independent electrician's assessment of the existing service, the solar backfeed design and any additional loads such as EV charging. Do not presume a $4,130 panel replacement is mandatory merely because one contractor included it. If the panel is unsafe, undersized or otherwise noncompliant, replacing it may be the sensible choice.
2. Can separate roofing, electrical and solar contractors reduce the cost?
Sometimes. Get a combined, turnkey proposal and separate written bids for roof, electrical and solar work. The separate bids may identify a lower total or a better specialist for each trade. The turnkey approach can reduce coordination burdens because one firm manages scheduling, permits and roof-penetration responsibilities.
The catch is accountability: when a roof leaks or an inspection fails, separate contractors may disagree over who is responsible. Before hiring, specify who designs the roof attachments, who preserves or provides roof warranties, who installs flashing, who coordinates shutdowns, who pulls each permit and who pays to correct rejected work. Avoid making the homeowner the unwitting general contractor without a clear written plan.
Ask whether roofing and electrical work can be paid for separately rather than rolled into a long solar loan. Replacing a roof is a home-maintenance decision and should not automatically be justified with solar's projected electric-bill savings.
3. Do you actually need a main electrical panel upgrade?
Possibly, but 'solar requires a 200-amp panel' is not a universal rule. The answer depends on the existing panel rating and condition, busbar and main-breaker ratings, inverter output, conductor and service capacity, connection method, adopted electrical code and the serving utility's requirements.
Ask a licensed electrician and the installer to evaluate feasible, permitted alternatives: a code-compliant load-side connection, main-breaker derating when a load calculation permits, a listed power-control or load-management system, a properly engineered supply-side connection, or a different inverter output/configuration. In some circumstances a compatible meter-collar or adapter is an option, but only if approved for the utility and equipment. None is an automatic shortcut or substitute for inspection.
A subpanel creates more circuit spaces but does not by itself increase an undersized utility service. The commonly discussed '120% rule' applies only to certain busbar configurations and code conditions; do not treat it as a blanket permission to connect solar. Require the contractor to identify the exact technical reason the upgrade is required and show the proposed one-line electrical diagram. Work on utility equipment and service connections must be coordinated with the utility and the permitting authority.
4. LADWP is not SCE: your utility's solar billing changes the economics
LADWP is a municipal utility with its own solar and net-energy-metering arrangements. It is not subject to Southern California Edison's Solar Billing Plan (often called NEM 3.0). A sales quote for an LADWP home must use the home's actual LADWP tariff, applicable net-metering rider and current utility rules, not a generic Los Angeles County forecast borrowed from SCE.
Under LADWP's applicable net-metering provisions, eligible customer generation is measured against electricity delivered to the home and credits are governed by the utility's tariff. The value and treatment of surplus, minimum bills, taxes and other charges must be confirmed on the homeowner's rate schedule; do not assume every solar kWh eliminates every dollar of the bill or that surplus will be paid out as cash.
Ask for a before-and-after bill model showing 12 months of consumption, solar production, direct use, exports, remaining electricity purchases, minimum charges and the applicable LADWP rate. Then test a conservative case: lower production, higher consumption, and changes in tariff. Solar can be financially sensible without eliminating your utility bill.
5. Would it make sense to repair the roof now and postpone solar?
Yes, particularly if the roof needs attention regardless of solar and the financing terms make the full project uncomfortable. Have an independent roofer estimate remaining roof life and safety concerns. Deferring critical roof repairs just to rush a solar installation can lead to a much larger removal-and-reinstallation expense later.
If replacing the roof now, tell the roofer solar may be installed later. Ask for a roof design compatible with future solar mounting, accurate roof measurements, warranties and any structural issues in writing. Get solar estimates before choosing roof materials or completing features that affect attachment.
The reason to install now rather than later should be a documented comparison of actual available incentives, utility economics, roof condition and loan terms—not sales pressure about a vaguely described rebate or deadline.
6. The loan payment may be the most expensive line item you overlook
A low monthly payment does not equal a low price. In the example, 180 payments of $530.64 would total $95,515.20, if that amount remained unchanged over all 15 years. Compare that with the $60,265 stated upfront project total: the difference is $35,250.20. Confirm whether the $530.64 payment is level for the entire term and whether a down payment or prepayment is assumed. Never equate 'the solar loan is $530 per month' with 'solar saves $530 per month.'
For an apples-to-apples illustration, borrowing $60,265 on a standard 15-year fully amortizing loan at a 7.24% nominal annual rate gives a payment of about $549.80 and total payments of roughly $98,963, excluding extra fees. At an illustrative 6% rate over the same 15 years and principal, payment would be around $508.70; over 20 years at 7.24%, payment would be lower but cumulative interest higher. These are mathematical illustrations, not available loan offers or guarantees.
Compare the installation cash price to the financed price. The Consumer Financial Protection Bureau has documented dealer-fee markups in some solar loans and payment structures that can increase if a presumed tax-credit prepayment does not arrive. Request the Truth in Lending disclosures, amount financed, APR, finance charge, total of payments, payment-change schedule, origination/dealer fees, collateral terms and early-payoff terms. Consider competitive credit-union or bank loans, home-equity products where appropriate, and cash-only solar proposals. Home-equity debt introduces risk to the house; evaluate it separately.
Leases and power-purchase agreements may lower upfront outlay but are not free systems. Compare ownership, contract escalators, annual payments, utility bill that remains, repairs, roof access, insurance, resale transfer and buyout terms. A third-party owner's possible business tax incentive does not automatically become a homeowner tax credit or a guaranteed price reduction.
7. Important 2026 tax and rebate realities
Federal: The IRS says the former Section 25D residential clean energy credit is not available for property placed in service after December 31, 2025. Do not subtract a presumed new 30% homeowner credit from a 2026 cash or loan quote. Commercial or third-party-owned projects involve different eligibility and tax rules; an installer must not present those as a personal homeowner benefit without explanation.
California: The State Board of Equalization describes an active solar energy system new-construction property-tax exclusion scheduled to sunset January 1, 2027 under the cited law. The exclusion is not a cash rebate and does not mean an older home receives a reduced existing assessment. Confirm qualifying completion and current law with your county assessor.
LADWP: Check the utility's own solar-program pages for the currently available programs, applications and rules. An installer promising a specific LADWP cash rebate must identify the exact active program and verify eligibility. Some LADWP arrangements, such as Solar Rooftops, involve utility ownership and payments for rooftop use rather than a homeowner purchasing panels and receiving conventional bill savings.
California SGIP: Battery incentives are highly category-, utility-, income-, program- and funding-dependent, and published budgets can change. Verify eligibility and funds with the official Self-Generation Incentive Program administrator before including a rebate in a contract or loan calculation. Programs offered by Clean Power Alliance to qualifying SCE-area customers are not automatically available to LADWP customers.
8. How to judge whether solar is worth it for your particular house
Start with 12 months of electric bills and, if possible, interval usage. Add anticipated loads such as EV charging and electric heating. Request monthly solar production and shade analysis; use the Department of Energy-supported PVWatts calculator as an independent reasonableness check, not a performance guarantee.
Compare at least three similarly specified bids, including a no-battery option if backup is not the goal. For each, calculate upfront price, financing over its full term, estimated remaining utility charges, operating costs and reasonably modeled lifetime production. Compare 'no solar / roof only / solar only / roof + solar / roof + solar + battery' where relevant.
A good outcome might be a smaller system, a roof replacement followed by solar later, a different financing product, or no installation now. Home Solar Simplified's purpose is to help you understand your options—not to push you toward a contract.
9. Rebuttals: seven claims homeowners should challenge
CLAIM: '$50,000 is the price of solar.' FACT: Request the solar-only line and separate roof, electrical, storage, permitting and financing. An all-in price is not the same as solar equipment cost.
CLAIM: 'You need more panels to save more.' FACT: Panel count alone is not meaningful. Ask for each module's watts, system DC kW, modeled annual kWh and how the size matches your utility usage and export compensation.
CLAIM: 'You must replace the whole main panel.' FACT: Sometimes necessary; sometimes a permitted alternate design works. Demand the one-line diagram, code-based explanation and independent electrical quote.
CLAIM: 'The utility bill disappears.' FACT: Minimum and non-bypassable charges may remain, and output and household usage change over time. Ask for a line-by-line post-solar bill model.
CLAIM: 'Zero down means there's no upfront cost.' FACT: The financed purchase price can embed markups and interest; compare cash price, principal, APR and total payments.
CLAIM: 'Everyone gets 30% back from the federal government.' FACT: The former homeowner Section 25D credit is unavailable for property placed in service after December 31, 2025. Distinguish any third-party business credit from the homeowner's own tax situation.
CLAIM: 'Sign today or lose your last chance.' FACT: Any real program deadline should be checked with the program administrator. Permits, utility approval, financing and roof suitability matter more than pressure.
10. Your step-by-step plan before signing
STEP ONE — Save the original quote, all revisions, every fee and your last 12 months of electric usage. Get a written explanation of the $1,168 discrepancy in the example if a comparable difference appears in your proposal.
STEP TWO — Ask an independent roofer whether roof replacement is required. Obtain a separate written scope and at least one competing bid. Have a licensed electrician review any panel-upgrade claim and acceptable alternatives.
STEP THREE — Request at least three solar proposals using the same annual kWh demand assumptions, system kW DC, expected production, solar-only cash price, financing details and warranties. Do not compare a roof-plus-solar quote with a solar-only quote.
STEP FOUR — Verify the contractor's California license and classification through the official CSLB lookup, insurance, permits, references and responsibility for warranty work. For other states, use that state's licensing board.
STEP FIVE — Confirm LADWP's actual tariff, export credits, service-connection process, permitted design, inspections and permission to operate; check official program funding yourself. Do not assume that an installed system can export before utility authorization.
STEP SIX — Compare total dollars paid over 15 or 20 years and the modeled electric bill that remains. Identify who owns the equipment, who handles repairs and what happens if you sell your home. Only then decide whether to proceed, change the design or wait.
Bottom line: The strongest solar quote is the one that survives questions
A $50,000-plus price tag is not automatically excessive, and a branded installer is not automatically your best or worst choice. What's unacceptable is an unexplained total, an upgrade without a clear technical reason, a production promise without data, or financing terms the homeowner cannot reconcile.
You should leave the process knowing exactly what your money buys, what your utility will still charge, what can go wrong, who fixes it and how the agreement affects your finances. Get educated, compare qualified professionals and move forward only on your own timeline and terms.
Try the solar quote comparison calculator
Change any figure to match your own proposal. The starting values illustrate the homeowner's LADWP quote—not an estimate or recommendation for your home. Numbers stay on this page.
Quoted payment compared with modeled payment: $19.16 lower per month. Confirm the lender's actual principal, rate, APR and payment schedule.
Important: This is a simplified fully amortizing fixed-rate loan illustration, using the entered annual rate as a nominal interest rate, not an APR-based Truth in Lending calculation. It excludes down payments, lender/dealer fees, insurance, taxes, variable rates, early payoff, future utility charges, and home-equity risk. The solar-only per-watt metric assumes the 13.44 kW case-study size; for another system, calculate solar price divided by its own DC watts. Negative net amounts do not imply guaranteed profit.
Frequently asked questions
Is $50,000 too much for solar panels?
Not necessarily for a complete project involving a new roof, service work or batteries. Separate those costs and compare the solar-only installed cash price, system size and equipment with equivalent local bids.
Is $37,497 for 13.44 kW of solar a good price?
It works out to about $2.79 per DC watt. That arithmetic alone does not establish whether the proposal is competitive: check equipment, project constraints, excluded work and current bids.
Can I install solar with a 100-amp electric panel?
Sometimes. It depends on the existing equipment, proposed inverter output, electric service, electrical code and utility approval. Have a licensed electrician evaluate permitted connection and load-management designs.
Does LADWP use NEM 3.0?
No. LADWP is a municipal utility with its own net-energy-metering rules, which should be checked using the customer's actual LADWP tariff and current utility documentation.
Is a $530 solar loan payment the same as $530 in savings?
No. A fixed debt payment is a financing obligation, while utility savings vary with solar production, consumption, tariff, export treatment and other bill charges.
Can I still get the federal 30% residential solar tax credit in 2026?
The IRS states that the former Section 25D homeowner credit is unavailable for property placed in service after December 31, 2025. Separate this from possible business incentives available to qualifying third-party owners.
Questions worth asking
- What is the exact cash price of the solar installation without roof work, panel upgrades or batteries?
- Why does the stated total differ from the sum of its line items, and are taxes, credits or fees missing?
- How many DC watts and how many modeled kWh per year am I buying?
- Does the proposed system size reflect my last 12 months of usage and future EV or electrification plans?
- Which utility tariff and net-metering rules did you use to calculate savings?
- Is the roof replacement truly necessary, and what is its independent, itemized scope?
- Can a licensed electrician show why the panel upgrade is necessary and which code-compliant alternatives were ruled out?
- What permits, interconnection charges and potential utility service work are included or excluded?
- Who is responsible for roof leaks, solar attachment warranties and coordination of separate contractors?
- What is the loan amount financed, nominal interest rate, APR, total of payments, finance charge and full payment schedule?
- Are dealer fees, tax-credit prepayments, loan step-ups or prepayment penalties involved?
- What electric bill will remain after solar under both optimistic and conservative production scenarios?
- If I want battery backup, which circuits, power level and hours are guaranteed by the proposed design?
- Which incentives are currently open for my exact utility account, and who receives them?
- Who holds the installation, roofing and electrical licenses, and who will service the system if the company closes?
- What happens to the loan, warranty or lease if I sell or refinance my home?
Related guides
Solar + Battery: what you need before signingAnother real solar quote: ownership, credit and backup risksHow to compare solar quotesCalifornia solar costs in 2026: compare real quote componentsCompare solar financing optionsSix questions to ask before signing a solar contractDo you need an electrical panel upgrade?Still researching solar?
Search homeowner guides by topic, electric utility, or location.
Sources and further reading
Sources reviewed: 2026-10-22. Confirm changing details with the official sources.
These links identify documents and resources used for this guide. Listing a source does not mean it was independently checked today. Utility rates, incentives, product specifications and program availability may change; confirm the latest version and effective date with the source.
IRS — Residential Clean Energy Credit (2025 placed-in-service cutoff)Consumer Financial Protection Bureau — Solar Financing Issue SpotlightCalifornia Public Utilities Commission — Solar Consumer Protection GuideLADWP — Residential Solar ProgramsCalifornia CSLB — Check a Contractor LicenseCalifornia Board of Equalization — Active Solar Energy System ExclusionCalifornia Self-Generation Incentive Program — Official PortalU.S. Department of Energy — Homeowner's Guide to Going SolarNREL — PVWatts Solar Production CalculatorConsumer Financial Protection Bureau — Home Equity Lines of CreditClean Power Alliance — Sun Storage Rebate (SCE/CPA territory, not generally LADWP)FTC — Solar Power for Your HomeStart with a home energy checkup
Organize your usage, home details and goals before comparing proposals.
Try the home energy checkupReady to compare companies?
Explore provider options when you are ready to request quotes.
Explore provider options